 ADAD
Updating your news feed...
NEWS EXPRESS is Nigeria’s leading online newspaper. Published by Africa’s international award-winning journalist, Mr. Isaac Umunna, NEWS EXPRESS is Nigeria’s first truly professional online daily newspaper. It is published from Lagos, Nigeria’s economic and media hub, and has a provision for occasional special print editions. Thanks to our vast network of sources and dedicated team of professional journalists and contributors spread across Nigeria and overseas, NEWS EXPRESS has become synonymous with newsbreaks and exclusive stories from around the world.
Loading banners
Loading banners...
Shares in artificial intelligence and technology firms have recovered slightly from an enormous sell-off that wiped trillions of dollars off stock values.
The tech-heavy Nasdaq stock index closed in positive territory following a market rout that began in the US on Thursday before spilling over to Asian and European markets into Friday.
Investors had been selling off tech shares in part due to concerns the Democrat victory in the midterm elections would mean slower artificial intelligence development.
However the latest US employment figures added to a mixed picture for American markets on Friday morning, with an unexpectedly strong 165,000 jobs added to the economy in September.
On Thursday, businesses closely linked to artificial intelligence development took a hammering on stock markets, particularly chip and semiconductor makers.
But the Nasdaq Composite bounced back slightly on Friday, ending the day up 1.1%, partly reversing some of its 5.5% fall.
The S&P 500, which tracks the share prices of the largest publicly-traded US companies, closed up 0.3%, while the Dow Jones Industrial Average was flat through the day before ending slightly down 0.4%.
Companies that lost hundreds of billions in market value recovered some ground on Friday, including Nvidia, SpaceX and Tesla.
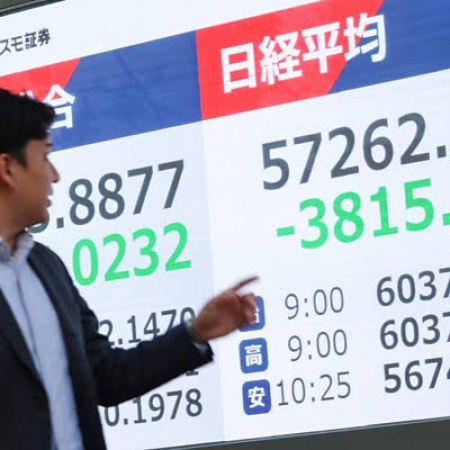
However, stock markets in Asia and Europe fared worse.
The Kospi in South Korea closed down 6% on Friday, with shares in chipmaker SK Hynix plunging more than 10%. European markets also fell, with the main indexes in Germany, France and Spain ending the day down.
In the UK, the FTSE 100, which tracks the largest companies on the London Stock Exchange, declined 1.01%.
In addition to the recent market volatility, UK traders were also digesting the latest Bank of England decision to raise interest rates and the signal that another rate rise could be on the cards to curb rising prices.
‘Market purgatory’
The market fluctuations also come after the sweeping Democrat victory in the midterm elections.
A number of Democrats campaigned for new rules and regulations for artificial intelligence (AI) and data centres, and the party has since won control of both houses of congress as well as key contests in states that have been part of the AI data centre race.
US President Donald Trump on Friday reiterated his supported for what he calls “super intelligence”, saying only “foolish leadership” would “say no to the riches they bring”.
However, there have also been concerns over whether the enormous amounts of money being spent on AI will pay off.
Russ Shaw, founder of global tech advocacy firm Tech London Advocates, said the election result was sending a message that a rethink was needed on AI.
“The incoming Congress is going to really focus on AI in a very dramatic way,” he told the BBC’s Business Today.
“I’m a big fan of AI, but I’m watching what these companies are doing, and they’re not communicating effectively at all, particularly in the US, about what the benefits of AI are all about.”
Pierre Baqué, chief executive of AI platform Neural Concept, said the share movements were a “necessary market correction” that reflected a legitimate concern about the amount of money being poured into AI infrastructure.
“The industry must move beyond unchecked infrastructure investment and demonstrate greater financial discipline,” he said.
“We are entering a critical transition phase, a market purgatory where raw tech must prove its widespread economic value.”
Dan Coatsworth, head of markets at AJ Bell, said it had been a brutal week for markets, and the key question was whether the jump in the S&P 500 and Nasdaq would be sustained.
“Once investors have had the weekend to catch their breath, next week could give a clearer indication of whether the tech trade is going down the pan or fighting back.”
As well as the fallout of the midterms and the plunge in artificial intelligence stocks, US traders will also be digesting the latest jobs figures.
And those numbers were better than expected: US employers added 165,000 new jobs in October, well above the average monthly increase and more than double what analysts had expected.
Overall the unemployment rate, which counts the number of people who are out of work but actively looking for a job, eased slightly to 4.1% from 4.2% in September.
The Bureau of Labor Statistics (BLS) said the unemployment rate has remained in the narrow range of 4.1% to 4.3% since March.
Neil Birrell, chief investment officer at investment firm Premier Miton, said while the jobs figures may feel like second billing to the market movements they were still important.
“The US economy is running hard which may mean the risks the markets are worrying about at the moment are not such a risk to the real economy as is being feared,” he said. (BBC)